Electric car insurance in the UK costs an average of £650 to £707 per year for comprehensive cover, roughly 10 to 15 per cent more than the £558 to £566 average for a petrol car. The gap has narrowed significantly in recent years as insurers have built up real claims data and the EV repair network has expanded, but it persists because electric vehicles carry a costly high-voltage battery, require specialist technicians for repairs, and face longer workshop wait times that drive up claim costs. By 2026 there are well over one million pure battery-electric cars registered in the UK, and with the 2035 deadline for ending new petrol and diesel sales firmly in place, that number will only grow.
That gap does not mean EV insurance is a bad deal or that it should put you off making the switch. It means you need to understand what you are buying, why the premium looks the way it does, and where the genuine opportunities to save lie. This guide covers all of that: from the insurance group ratings of the most popular UK models to the specific coverage questions that simply did not exist when you owned a combustion-engine car.
Why EV Insurance Costs More in the UK
When an insurer calculates your premium, it is pricing the expected cost of claims against your vehicle over the policy term. For electric cars, three factors consistently push that expected cost above what a comparable petrol or diesel model would generate.
Battery replacement costs. The high-voltage traction battery is the single most expensive component of any modern EV. Replacement costs range from around £4,000 at the lower end to £18,000 for large premium SUVs, with most mainstream models landing between £5,500 and £11,500 fitted, according to data compiled by carinsuranceexpert.co.uk in 2026. A significant collision can mean the insurer writes the car off not because the bodywork is unrepairable, but because fixing the battery pack safely costs more than the vehicle is worth on the open market. Insurers typically declare a write-off when repair costs exceed around 50 to 60 per cent of the car's pre-accident market value - a threshold hit far more easily on an EV than on a petrol equivalent of the same age.
Specialist repair requirements. High-voltage systems cannot safely be worked on by a standard garage without specific training, certification and equipment. Many manufacturers - Tesla being the most prominent example - require that repairs be carried out by their own approved technicians or authorised bodyshops. That network is geographically concentrated, which means vehicles may need to travel further for repairs, wait longer for appointment slots, and spend more days drawing on a courtesy car. Each of those factors adds to a claim's overall cost.
Parts availability and longer repair times. EV-specific components such as battery modules, thermal management systems and onboard chargers are produced by a relatively small number of global suppliers. Supply disruptions extend repair timelines, and longer repairs mean higher costs across the board. Insurers have had to price this unpredictability into EV premiums from the start.
The good news is that as the EV repairer network expands and insurers accumulate years of real claims data, the premium gap is narrowing. For smaller, more affordable EVs such as the Nissan Leaf or Volkswagen ID.3, some insurers already quote competitively against petrol equivalents. The gap is most pronounced at the performance and premium end of the market.
What Your EV Insurance Policy Actually Covers
UK motor insurance law requires every vehicle to carry at least third-party cover, which protects others in the event of injury or damage you cause. Third-party, fire and theft adds cover if your vehicle is stolen or destroyed by fire. Comprehensive cover - the level most EV owners should seriously consider - adds protection for damage to your own vehicle including in at-fault accidents.
For electric car drivers, four coverage areas within a comprehensive policy deserve particular attention before you buy.
Battery Damage vs Battery Degradation
This is the most important distinction in EV insurance, and it is one that catches out a significant number of buyers.
Battery damage - caused by a collision, flood water entering the battery enclosure, fire or vandalism - is covered under a standard comprehensive motor policy in the same way that bodywork damage is covered. If a crash compromises a battery module, your insurer should pay to repair or replace it, subject to the usual policy terms and your chosen excess.
Battery degradation - the gradual, unavoidable reduction in maximum capacity that all lithium-ion batteries experience over time and charge cycles - is not covered, and should not be. Degradation is wear and tear. Motor insurance has never covered a petrol car's exhaust corroding or its clutch wearing through. The progressive loss of a few percentage points of your EV's range per year falls into exactly the same category.
Complications arise in the grey zone between the two. A collision that directly impacts the battery enclosure may also accelerate apparent degradation in the affected cells. Some policy wordings address this explicitly; others do not. When comparing quotes, look for how the policy handles partial battery damage - whether it covers individual module replacement or requires whole-pack replacement, whether any minimum battery-health threshold might affect a future claim, and whether a leased battery is covered separately from the vehicle. Some specialist EV policies offer new-for-old battery replacement in the first few years of cover, which is worth asking about explicitly when you request a quote.
Because EV battery costs make write-offs more common than they are for equivalent petrol cars, it is also worth considering GAP insurance, which pays the difference between your insurer's write-off settlement and the amount you originally paid or still owe on a finance agreement. BIBA has documented individual shortfalls exceeding £19,000 on financed EVs where the motor insurer's settlement fell short of the outstanding finance balance.
Charging Cables and Portable Equipment
A good-quality Type 2 charging cable - the UK and European standard for AC home and public charging - costs anywhere from around £100 for a basic unit to several hundred pounds for a premium smart cable with built-in metering. Losing one to theft from your car is a genuine and recurring nuisance.
Cables stored in the boot or passenger compartment are typically covered under the personal belongings section of a comprehensive policy. However, many standard policies set personal belongings limits at £100 to £250 - barely enough to cover a decent cable. Check this figure carefully when you compare. Specialist EV insurers and an increasing number of mainstream providers have responded to this gap with higher limits or dedicated charging-equipment cover.
A cable left plugged into a public charger overnight, unattended while you sleep or work, raises additional questions about what counts as being within the vehicle for insurance purposes. Check the exact policy wording if you regularly charge publicly and leave your cable connected for extended periods.
Home Wallbox Chargers
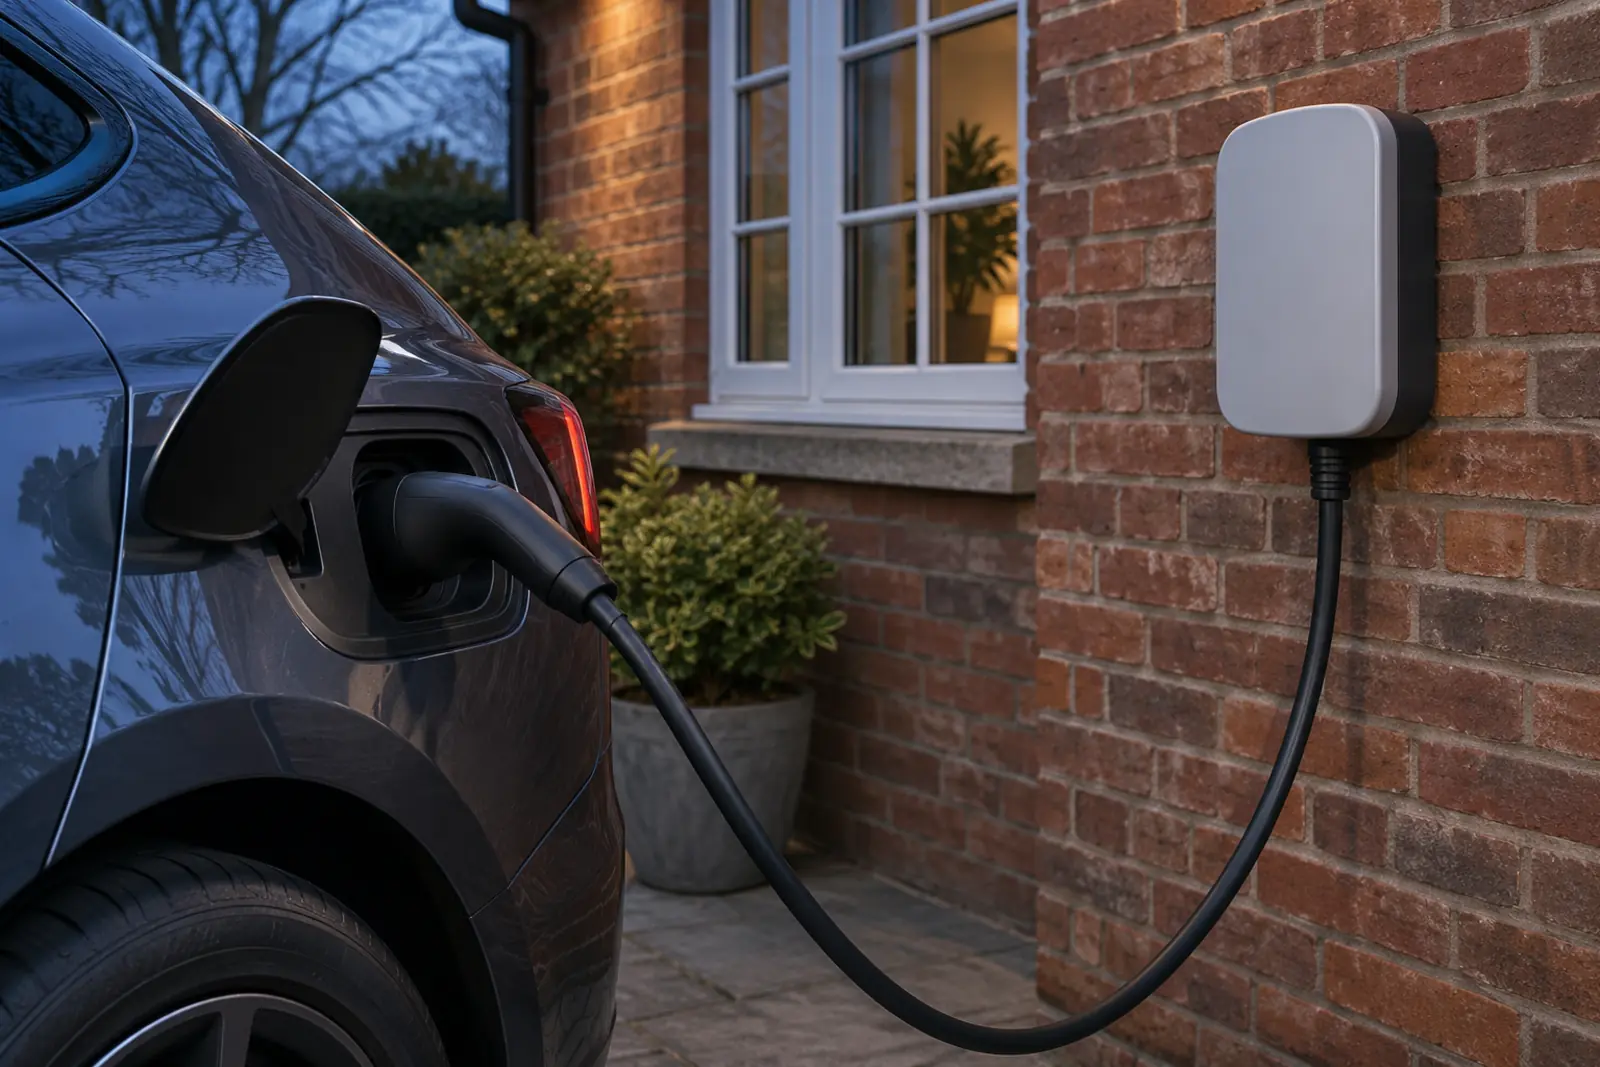
A dedicated 7kW home wallbox - the most common home charging solution for UK EV owners - is a fixed installation and is generally covered under your home insurance rather than your motor policy, treated as a permanent fixture on the property. There are gaps though: damage during installation, electrical surges affecting the unit, or fire caused by a faulty charger may need to be mapped across both your home and motor policies to understand which responds and whether any exclusions apply.
Several mainstream and specialist EV insurers have begun addressing this directly. Aviva's EV-specific product explicitly covers charging cables, the wallbox unit and personal injury sustained while charging, along with an out-of-charge recovery service to the nearest charge point. Admiral's dedicated EV policy includes home wallbox protection and access to Zoom EV, a benefits platform for electric car owners, included free for the first year, with out-of-charge recovery included as standard. LV= Insurance's EV product covers charging cables and equipment as standard, and explicitly extends that protection to batteries leased separately from the vehicle. If your insurer's documents say nothing about home charger cover, ask the question in writing before you sign so you know exactly where you stand.
Like-for-Like Courtesy Cars
If your EV is off the road for specialist repairs - which can run to weeks when approved bodyshop availability is limited - your insurer should provide a courtesy vehicle. The practical problem for EV owners is that standard policies typically supply whatever small petrol car their approved repairer has available. In an analysis of UK car insurance policies, Which? found that only around 10 per cent of the policies it reviewed even mentioned potentially offering an electric or hybrid courtesy vehicle during repairs.
For EV owners without another vehicle at home, a petrol courtesy car means adapting to fuel stops you are not used to and covering fuel costs that your policy does not reimburse. If a like-for-like electric replacement matters to you, check the courtesy car terms explicitly before buying: LV= offers an electric or hybrid hire car if you add optional hire car cover, while Aviva and Admiral include courtesy car provisions as standard. Some specialist EV policies go further and guarantee an equivalent-size electric replacement.
EV Insurance Groups - Where Popular UK Models Sit
The UK's insurance group system, managed by Thatcham Research and running from group 1 (least expensive to insure) to group 50 (most expensive), applies to electric vehicles in exactly the same way it applies to petrol and diesel cars. Group ratings are set by factors including new vehicle price, performance figures, parts costs, repair complexity and security provision. Most mainstream EVs sit in the middle to upper portion of the scale, reflecting their purchase price and parts costs even when their real-world performance is modest.
Here is where some common UK models currently sit. Always verify the exact group for your specific trim and model year using the ABI's online group rating tool, as ratings are periodically reviewed and can differ between variants of the same car:
- Volkswagen ID.3 - Groups 18 to 25 depending on power variant and trim, making it one of the most affordable mainstream EVs to insure
- Nissan Leaf - Groups 21 to 28; typical comprehensive quotes start from around £400 per year for an experienced driver with a clean record
- Volkswagen ID.4 - Upper 30s for most variants, reflecting its larger platform and higher parts cost
- Tesla Model 3 - Groups 32 to 50 depending on variant and model year. The January 2026 Standard trim sits at group 32; the outgoing RWD (2023 to 2025) at group 36; the Long Range RWD at group 38; the Long Range AWD at group 41; and Performance AWD variants at groups 48 to 50. Typical quotes for an experienced driver with a clean record start from around £780 per year for entry variants and rise considerably for Long Range, Performance and older pre-2023 models
- Kia EV6 - Upper 30s to mid-40s
- BMW i4 - Upper 40s, reflecting its premium price point and specialist repair network
The practical implication is straightforward: if you are choosing between two similarly capable EVs and one sits several insurance groups lower than the other, the lower group will save you money on premiums every year you own the car. Factor this into your purchase decision alongside the vehicle price and WLTP range figure.
Specialist EV Insurers - What the Best Policies Include
Standard comparison sites include mainstream insurers who write EV policies alongside their general motor book. This produces adequate cover in most cases, but specialist or EV-focused policies often offer meaningfully better terms in the areas that matter most for electric car owners.
Aviva's EV-specific offering has received consistent recognition for the breadth of its cover - battery damage protection, explicit cable and wallbox cover, an out-of-charge recovery service and a 5-star Defaqto rating make it a benchmark against which to compare others. LV= was among the first mainstream insurers to include a flat battery recovery service as a standard feature rather than a paid add-on: if your charge runs out on the road, LV= will arrange a tow to the nearest charge point without affecting your no-claims discount, and the policy explicitly covers leased batteries. Admiral's dedicated EV policy includes home wallbox protection and access to the Zoom EV platform, which gives policyholders a year of EV-specific benefits free of charge, with out-of-charge recovery included as standard.
Beyond the big names, a number of independent EV-focused brokers and underwriters have emerged to serve the specific needs of electric vehicle owners - particularly around battery cover terms, cable limits and integrated breakdown assistance. When you compare quotes, search specifically for electric car insurance or EV insurance rather than relying solely on a generic comparison result, and read each policy summary carefully for the coverage areas covered in this guide. The difference between a standard and a specialist policy can be significant, and the premium difference is often smaller than you might expect.
Breakdown Cover for Electric Vehicles - Why It Works Differently
The most important single difference between EV and petrol breakdown cover is what happens when you run out of energy. A standard breakdown van cannot provide a roadside fuel top-up for an electric car. The response available to a recovery patrol arriving at a flat-battery callout is more limited, and this has real implications for the cover you need to buy.
The AA attended more than 190,000 EV breakdown callouts in 2025 alone, with flat batteries and charging system faults among the leading causes. When a flat battery is the issue and no mobile charging unit is available, the typical response is either a flatbed recovery to the nearest working charge point or onward transport to a destination of your choice subject to the mileage limits in your policy.
Flatbed recovery matters for a specific technical reason: most manufacturers specify that their electric vehicles must not be towed behind a recovery vehicle with wheels on the ground, because doing so causes the motor to spin and can damage the drivetrain electronics and regenerative braking system. A flatbed, or a system such as the RAC's patented all-wheels-up rapid recovery, avoids this risk. Before you buy breakdown cover, confirm that flatbed is included as standard where the manufacturer requires it - not as a chargeable upgrade.
RAC's EV Boost service addresses another gap in the market: specially equipped vans can provide a roadside charge of roughly 10 miles, enough to reach the nearest charge point without recovery at all. The service is not available everywhere, but the network is expanding. It is worth noting which breakdown providers operate these mobile chargers in your typical driving area.
Two further points deserve attention. If a public charge point fails during a session and leaves you without enough range to reach another charger, that is a charge point operator problem - contact the network's helpline directly rather than your breakdown provider. And some breakdown providers now include a specific callout if your home charger fails to charge the vehicle overnight, which is useful cover given that home charging is how most UK EV owners start each day. Check whether this is included or available as a reasonably priced add-on.
How to Reduce the Cost of EV Insurance in the UK
The standard premium-reduction levers apply as much to electric cars as to any other vehicle: shop around thoroughly at renewal rather than accepting the automatic rollover quote, maintain a clean no-claims record, consider increasing your voluntary excess if you can comfortably absorb the risk in a minor claim, and consider adding approved security devices if your model's insurance group rating is driven partly by security concerns. The guide to no-claims discount explains how it builds and what it is worth, and our car insurance excess guide covers compulsory versus voluntary excess and how to set the right level. EV owners also have some additional options worth exploring.
Telematics or black box cover. EV drivers tend to have driving habits that score well on telematics systems - smooth acceleration and regenerative braking produce a driving profile that most scoring algorithms reward. If you are a newer driver or returning to driving after a break, a telematics policy can produce significant savings. The black box car insurance guide explains exactly how these policies work and whether they suit your situation.
Dash cam. Fitting a dash cam can support your position in a disputed claim and some insurers offer a small premium reduction for verified camera use. The guide to dash cam car insurance covers which insurers recognise camera footage and what to look for in a policy.
Garage parking. An EV parked and charged in a locked garage overnight presents a substantially lower theft and damage risk than one left on the street. Most insurers discount for this. Confirm with your insurer that plugging the car in to charge while it is inside a locked garage still qualifies for the discount - most accept this without restriction, but it is worth checking.
Accurate annual mileage declaration. EV owners often cover fewer miles than they did in their previous petrol car, particularly in the first year as charging habits settle. If your genuine annual mileage is lower than average, declare it accurately - mileage is a genuine pricing factor and a lower honest figure will generally reduce your quote. Under-declaring mileage knowingly is misrepresentation and can void a claim.
Named driver considerations. Adding an experienced named driver with a long clean record can reduce your premium. Adding a younger or less experienced named driver will generally increase it. Never add someone as a named driver as a way of misrepresenting who the main user of the vehicle is - that is fronting, which is insurance fraud, voids the policy and can result in prosecution. The guide to car insurance fronting explains this in full.
Compare specialist EV providers directly. Major comparison sites are a solid starting point but do not always include every specialist EV broker or underwriter. Running a direct search for EV-specific providers alongside your comparison results can surface policies with better battery cover terms and more competitive pricing, particularly for higher-group models where the mainstream market prices conservatively.
Driving Your EV in Europe
The post-Brexit rules for driving a UK-registered vehicle in Europe have settled, but preparation is still needed before any trip. For most EU member states and associated countries including Norway, Iceland, Liechtenstein and Switzerland, UK motor policies automatically provide the minimum level of third-party cover required by local law. You are not currently required to carry a physical green card when entering these countries, though you should always carry proof of insurance.
Where the distinction matters for EV drivers is in what level of cover actually applies abroad. Many UK policies automatically reduce to third-party when driven in Europe, even if you hold comprehensive cover at home. If you want comprehensive protection during a European trip - covering your own vehicle in an at-fault collision, for example - check whether your policy includes this or whether a small premium extension is available. The guide to UK car insurance in Europe covers the full rules on green cards, cover levels and what to carry. Contact your insurer before booking the crossing, not the night before you leave.
Also note that the old GB oval sticker is no longer valid for European travel. You need a UK sticker on the rear of your vehicle, or your number plate must already incorporate the UK identifier within its design.
EV-specific European considerations go beyond the insurance document. Charging infrastructure quality varies considerably by country - the Netherlands, Germany and the Nordic countries have mature rapid-charging networks, while some other destinations remain patchier. Your breakdown cover should explicitly state how it handles flat-battery recovery abroad, because standard European breakdown policies sometimes exclude battery-related events or provide a lower level of response than you would get at home. Check the small print for the specific countries on your route before you travel.
Frequently Asked Questions
Is electric car insurance more expensive than petrol car insurance in the UK?
In most cases yes, but the gap has narrowed considerably. In 2026, the average comprehensive EV premium runs around £650 to £707 per year, compared with roughly £558 to £566 for petrol cars - a difference of approximately 10 to 15 per cent on average. Smaller models like the Volkswagen ID.3 sit much closer to petrol equivalents, while performance models attract a larger premium gap. Shopping around, including with specialist EV providers outside the mainstream comparison sites, can substantially reduce what you pay.
Does car insurance cover damage to my EV's battery?
Accidental damage to the battery pack from a collision, fire, flood water intrusion or vandalism is covered under a comprehensive motor policy. Normal battery degradation - the gradual loss of maximum capacity over time and charge cycles - is wear and tear and is not covered by any motor insurance policy. Before buying, check the policy wording for minimum battery-health thresholds, whether it covers partial module replacement or only full-pack replacement, whether a leased battery is treated separately, and whether a new-for-old battery option is available in the first years of cover.
Are my charging cable and home wallbox covered by motor insurance?
A cable kept inside the vehicle is usually covered under the personal belongings section of a comprehensive policy, but limits vary and some policies set these as low as £100 to £250 - check this figure carefully. A fixed home wallbox charger is typically covered under your home insurance as a permanent fixture rather than under your motor policy. Specialist EV insurers including Aviva and Admiral explicitly extend motor cover to cables and wallboxes, so ask specifically about this when you compare quotes if it matters to you.
What breakdown cover do I need for an electric vehicle?
Look for cover that explicitly treats a flat battery as a covered breakdown event, includes flatbed recovery as standard where the manufacturer requires it, and states clearly what happens if you run out of charge away from a charge point. The RAC offers EV Boost vans that can provide a short roadside charge. The AA has EV-trained patrols and attended more than 190,000 EV callouts in 2025. Check also whether the policy covers a home charger failing overnight, and whether European breakdown assistance extends to flat-battery scenarios if you plan to drive on the continent.
Is GAP insurance worth it for an electric car?
GAP insurance is worth considering for any financed or leased EV. Because battery costs make write-offs more common on electric cars than on petrol equivalents, the settlement your motor insurer pays may fall well short of what you paid or still owe on a finance agreement. BIBA has documented individual write-off shortfalls exceeding £19,000 on financed EVs. GAP cover pays the difference. The guide to GAP insurance explains how it works and whether the cost is justified for your situation.
Do I need a green card to drive my EV in Europe?
You are not legally required to carry a physical green card when driving in most EU member states and in countries such as Norway and Switzerland, as UK motor policies automatically provide minimum third-party cover in those territories. However, confirm with your insurer before travelling that comprehensive cover extends to Europe - many policies revert to third-party abroad unless you request an extension. Always carry proof of insurance and display a UK sticker on the rear of your vehicle, not the old GB oval.
Which UK insurance group is my electric car in?
EV insurance groups follow the same 1 to 50 scale as petrol and diesel cars, managed by Thatcham Research. As a general guide: the Volkswagen ID.3 sits in groups 18 to 25, the Nissan Leaf in groups 21 to 28, and the Tesla Model 3 in groups 32 to 50 depending on variant (Standard at 32, 2023-2025 RWD at 36, Long Range RWD at 38, Long Range AWD at 41, Performance AWD at groups 48 to 50). Groups vary by trim and model year, so always use the ABI's online group rating tool to check your specific variant before you buy. A lower group typically means a meaningfully lower annual premium, so it is worth checking group ratings before you commit to a model.